The decision and the story that follows
There are two different things I would like to preserve about an investment: what happened to it, and why I thought it made sense at the time. The first is relatively easy to record. Prices, transactions, and dates leave a trail. The second is more fragile. Once I know the result, my memory begins arranging the past around it.
A company does well, and the signs of its strength seem to have been sitting in plain sight. An investment disappoints, and the weaknesses appear more obvious than they once were. In either case, the ending can make the beginning look simpler. The uncertainty that surrounded the actual decision quietly disappears from the account.
This is one reason I am interested in keeping a record of my investment reasoning. Not a detailed defense of every purchase, and not a diary built around daily price movements. I want something smaller: a trace of what I knew, what I expected, and what remained unresolved before the result supplied its own explanation.
For me, investing is ultimately connected to having more freedom over my time. Learning from it matters, but so does keeping that learning honest. A record of reasons may help me distinguish an improved understanding from a more convincing story about something that has already happened.
How the ending changes the beginning
Psychologists use the term hindsight bias for the tendency to see an outcome as more predictable after learning what happened. The description feels familiar. Once an event has an ending, it becomes easier to arrange earlier information into a sequence that seems to lead toward it.
At the moment of an investment decision, however, information does not arrive as a finished explanation. There may be encouraging business results alongside an uncertain outlook. A familiar service may be useful without its shares being attractively priced. Several interpretations can remain plausible at once.
Afterward, one of those interpretations fits the outcome better than the others. It becomes tempting to remember that interpretation as the one I held firmly all along. An expectation that was tentative in my mind acquires sharper edges in memory.
There is a related difficulty in judging a decision mainly by its outcome. A profitable result can follow weak reasoning, just as a disappointing result can follow a reasonable assessment of incomplete information. This does not make results irrelevant. It means the result and the quality of the original reasoning need separate attention.
I would like to be able to say that I considered something carefully without requiring the outcome to prove me right. Equally, I would like a favorable result to leave room for the admission that I overlooked something important. Both become harder when the only surviving record is the final number.
A dated note beside the numbers
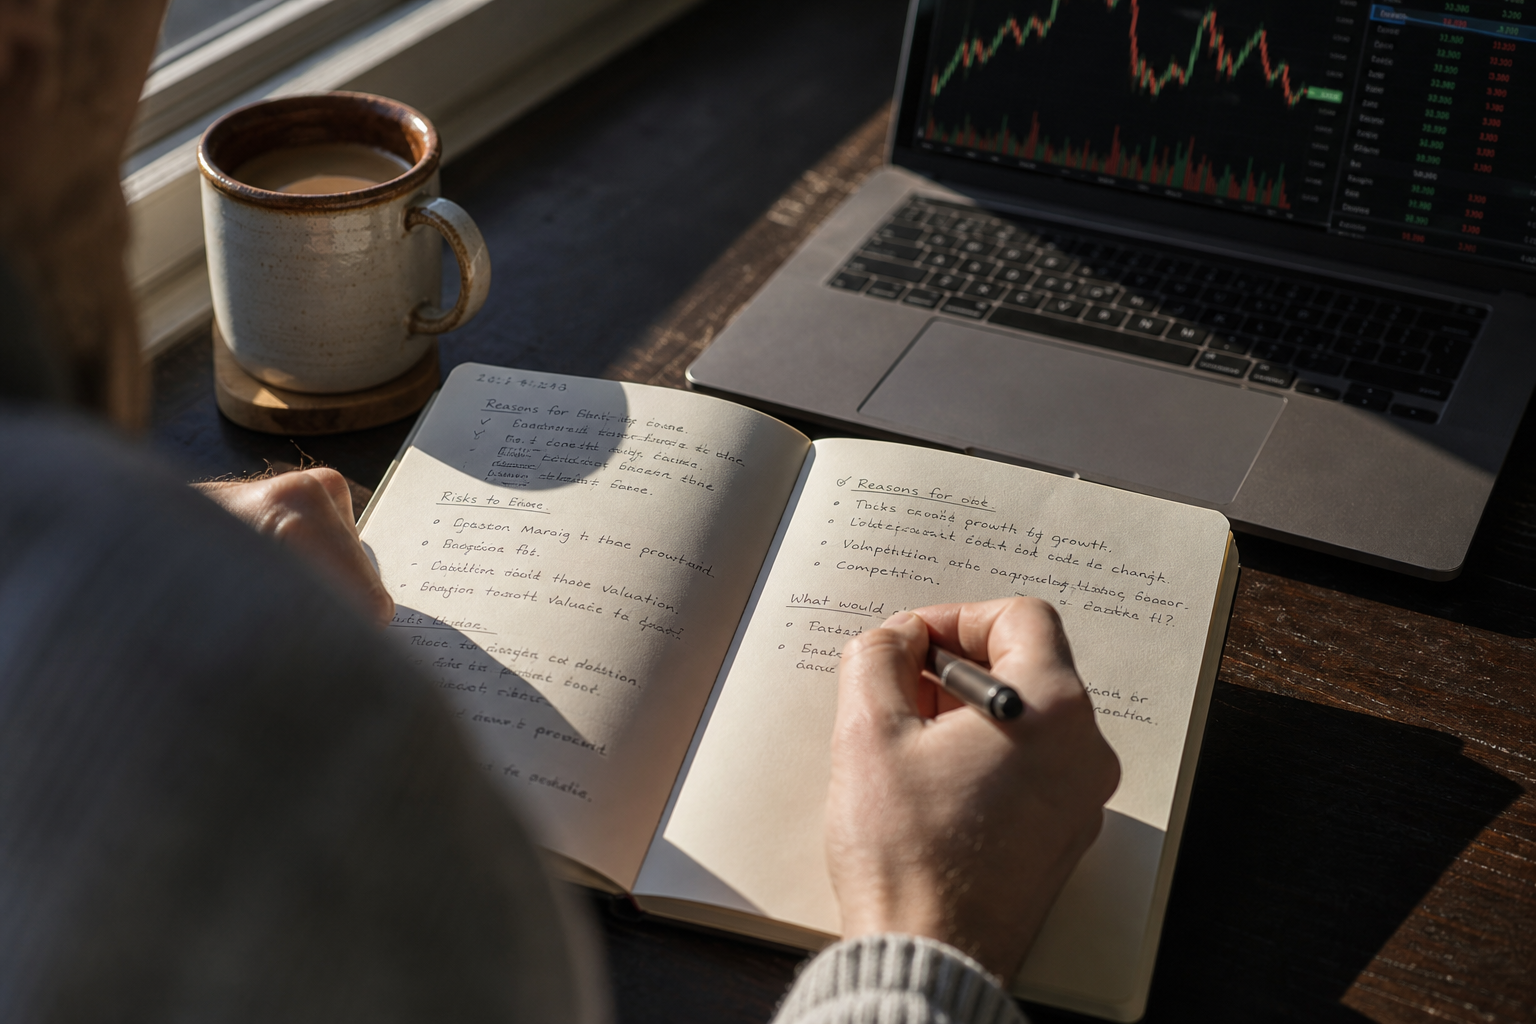
An account statement records what I did. A short note can preserve something of the situation in which I did it. That difference reminds me of the purpose of a laboratory notebook: keeping observations and expectations in sequence, rather than reconstructing the entire process after seeing the result.
An investment is not a controlled experiment. A business operates among changing customers, competitors, costs, and expectations. Still, there is something useful in the modest discipline of writing an expectation down before finding out how events unfold. The date keeps the thought attached to a particular state of knowledge.
The note I have in mind would begin with the reason for my interest. In my own long-term investing, that often starts with liking a company and seeing how its products or services support ordinary life. That is a meaningful starting point for me, but it is not yet a complete investment argument.
I would also want to record what I had actually examined: the business performance, the share price, and the assumptions connecting the two. If my understanding was shallow, the note should say so. A clear statement of limited knowledge seems more useful than polished language that makes a rough impression sound like analysis.
Beside that, I would leave room for uncertainty. Perhaps I understand why a service is useful but not how durable its profitability might be. Perhaps I like the business while remaining unsure about its valuation. Recording those limits would preserve the unfinished character of the decision, which is precisely what hindsight tends to smooth away.
Reviewing without putting the past on trial
My present approach is mainly long-term ownership of individual companies I like. I tend to begin with small positions, and I do not generally make cutting losses part of that personal approach. This is my own style, not a general rule. Liking a company does not protect an investment from loss, and a small starting position does not make an uncertain business predictable.
A record of reasons would give me a quieter way to examine that attachment. There is a difference between continuing to hold because the original reasoning remains persuasive and continuing to hold because I have become accustomed to the position. Without a written record, those explanations can easily borrow each other’s language.
On review, I would want to separate changes in the business from changes in my understanding. Sometimes new information genuinely alters the picture. Sometimes the information was available, but I failed to notice its importance. Sometimes the original assessment was reasonable and events simply developed differently. These are not identical lessons.
The purpose would not be to prosecute my earlier self. A person deciding under uncertainty cannot possess the knowledge that arrives later. I would rather judge the care of the process using what was available then, while using later evidence to improve how I think now.
I am also interested in studying swing trading. If I explore that style, I would need to learn its different treatment of timing, risk, and loss-cutting rather than carry my long-term habits into it unchanged. A dated reason would help identify which kind of decision I believed I was making. Otherwise, even the intended holding period can become part of the story rewritten afterward.
A record small enough to keep
I know my tendency to make plans more elaborate than I can comfortably maintain. A journal with too many fields could turn a useful pause into another task to avoid. I do not need a miniature research report each time I make a decision.
A few plain sentences may be enough for the record I want: the reason for the decision, the information behind it, the uncertainty I could see, and the developments that would deserve another look. These are not promises about the future. They are a description of where my thinking stood.
I would prefer later reflections to sit beside the original note rather than replace it. If my view changes, a new dated entry can explain the change. That leaves the earlier uncertainty visible. It also makes learning easier to recognize: not as a claim that I understood everything from the beginning, but as a difference between two records of thought.
This fits the distinction I try to make between time for thinking and time for acting. The reasoning belongs to a deliberate pause. Once a decision has been made, the record can hold it without requiring me to reconstruct it whenever the price moves. Review can then be an occasion for examination rather than an endless internal argument.
What I want to preserve is not the image of a consistently correct investor. It is continuity with the person who made the decision before the outcome was known. That person had reasons, doubts, and gaps in understanding. Leaving a faithful record seems a modest way to respect that uncertainty—and to learn from it without quietly changing what it was.
This essay is a personal reflection, not investment advice. Investing involves risk, including the possible loss of capital.
This essay reflects my personal thoughts and experience. It is not financial or investment advice.